Products
Embedded Payments
Payment infrastructure built into your product, invisible to users, and fully under your brand. Issue accounts, collect funds, trigger payouts, and automate transfers through one integration.
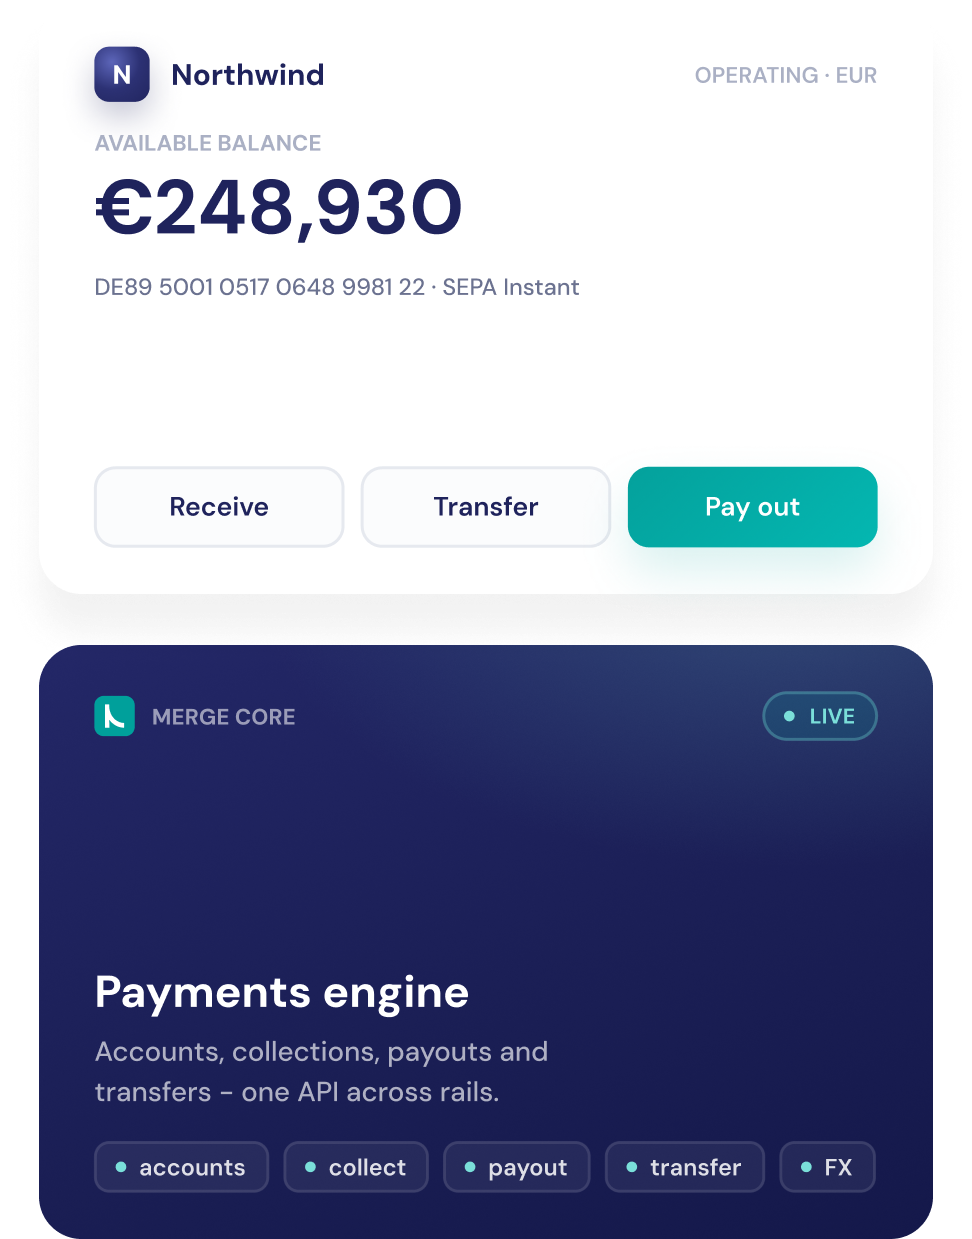

When people talk about embedded payments, they sometimes imagine a checkout widget. Unispar's solution is much more than that.

End customers don't need to know who Unispar is; they simply experience a fully branded flow that funds accounts, collects from buyers, pays sellers or moves money internally.

Through a single integration, you can wire onboarding, funding, collections, disbursements, payouts and internal transfers to specific events in your product.

This is the difference between a widget and a true embedded payment solution: it's the entire payments stack integrated into your application.
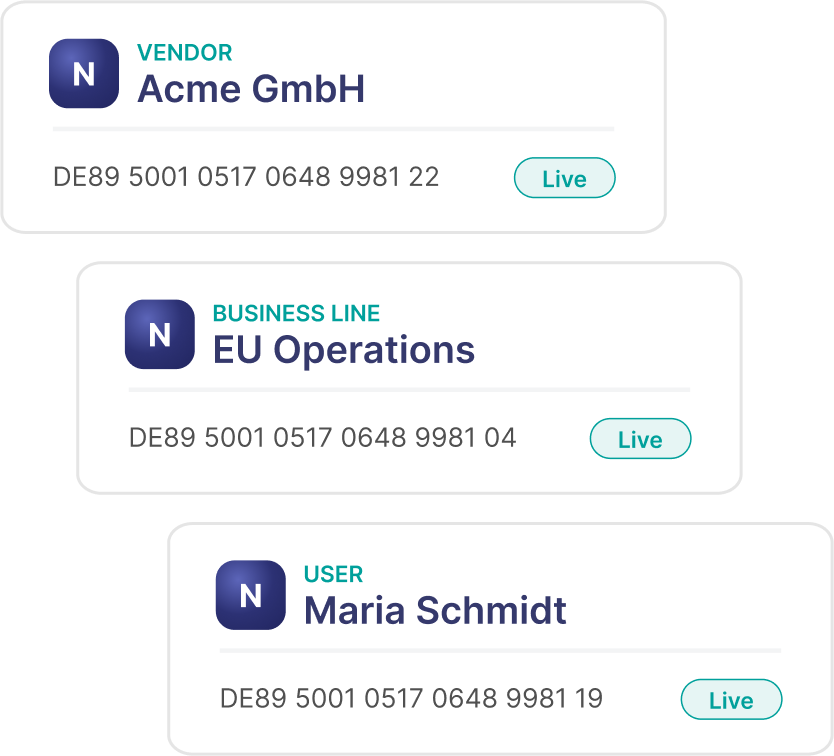
With Unispar, you can create named sub‑accounts, IBANs and virtual account numbers directly in your product. These accounts can be assigned to:
Unispar supports the payment layer within broader embedded finance solutions, giving platforms the infrastructure to collect, hold, move, and distribute funds through branded experiences:


Unispar makes it straightforward to embed payment flows across your platform. The process can be broken down into four steps:
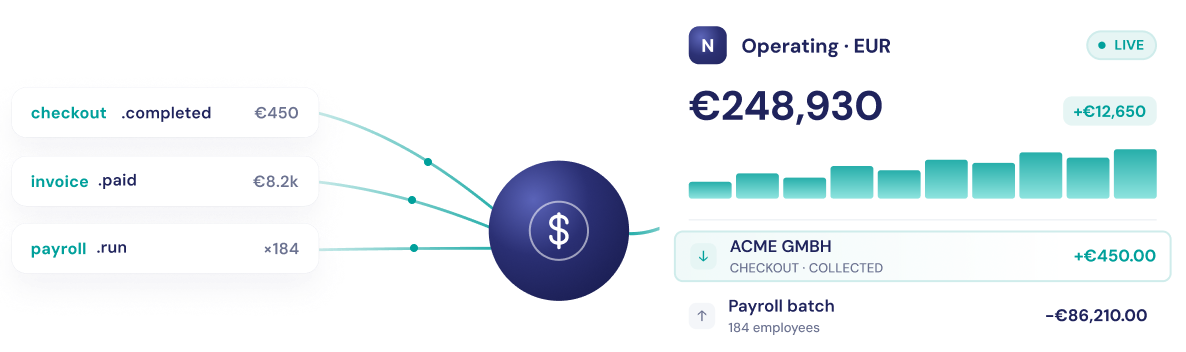
Traditional payment tools handle single transactions. Unispar enables multi-step flows, collecting funds into named accounts, holding them in segregated sub-accounts, and distributing them on schedules or triggers, ideal for payouts, payroll, contractor payments, and treasury sweeps, with full lifecycle control.
A raw payment API triggers transactions. Unispar provides a full embedded payment solution that combines:


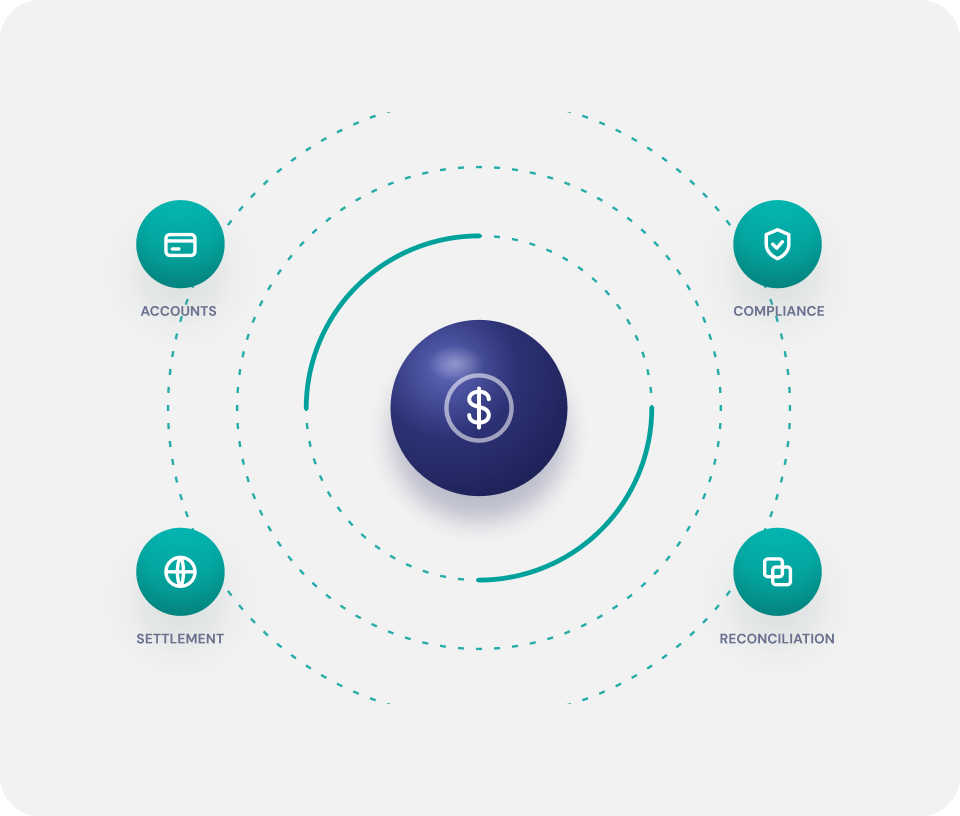
Unlike standalone payment APIs, Unispar delivers a complete embedded payment solution, accounts, compliance, settlement, and reconciliation in one integration.
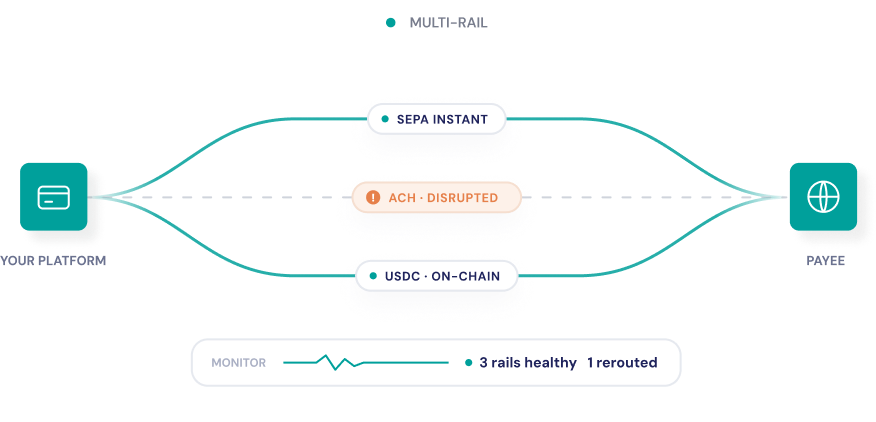
Payment systems have become critical infrastructure. Even brief outages have tangible impacts on individuals and businesses. Unispar is designed around resilience from the ground up:
This reliability focus is critical for enterprise‑grade embedded payments, without making unsupported uptime guarantees.


Launch branded accounts, collections, payouts, and programmable payment flows through one infrastructure layer. Unispar handles the payment rails, compliance workflows, and settlement infrastructure behind the scenes, so your team can focus on the product experience.

Embedded payments are payment capabilities built directly into a platform, app or product experience. With Unispar, the client controls the branded customer experience while Unispar powers the infrastructure in the background. The platform provides account infrastructure, payment flows, compliance workflows, settlement connectivity and structured payment data without exposing end users to a separate provider.
Embedded payment solutions go beyond raw API access. A payment API triggers a transaction, while Unispar provides the entire infrastructure behind the transaction: named sub‑accounts, IBANs, virtual account numbers, compliance workflows, stablecoin settlement rails, local payment connections and reconciliation data through a single integration.
Yes. Unispar can support embedded online payment solutions with named sub‑accounts, including IBANs and virtual account numbers. These accounts can be assigned per end user, counterparty, business entity, vendor or business line, giving platforms a branded account infrastructure without needing to build it directly.
Payment actions can be triggered by platform events across the customer lifecycle. Common triggers include onboarding, account funding, checkout or transaction events, marketplace seller payouts, contractor payments, payroll disbursements, treasury sweeps and internal transfers between sub‑accounts.
Unispar is relevant for embedded finance solutions because it provides the payment infrastructure layer behind branded financial experiences. Platforms can embed accounts, collections, payouts, stablecoin settlement, compliance workflows and reconciliation data into their product without stitching together multiple banking, payments and settlement providers. This unified approach avoids the operational fragility that arises when programs stitch together point solutions.